Earnings yield and FCF yield: pricing stocks like bonds
An earnings yield is a valuation multiple turned upside down. Instead of saying a stock trades at 20 times earnings, it says the earnings are 5% of the price paid. Free-cash-flow yield does the same with cash left after capital spending. Both describe what the market price buys relative to a chosen measure of output. Neither says what that output will be next year.
The rule that makes either ratio meaningful is simple: match the numerator to the claim priced in the denominator. Operating earnings belong over enterprise value, which prices the whole business. Cash available to equity belongs over market capitalization, which prices the shareholders' slice. Get that pairing right and a yield becomes a compact research question. Get it wrong and the ratio can look precise while comparing claims that belong to different people.
A yield is the inverse of a multiple
A multiple answers, "How many dollars of price am I paying for one dollar of a measure?" A yield reverses the question: "How much of that measure does one dollar of price represent?"
price/earnings multiple = market capitalization / net income
earnings yield          = net income / market capitalization

EV/EBITDA multiple      = enterprise value / EBITDA
EBITDA/EV yield         = EBITDA / enterprise value
That inversion is useful because the result reads like an annual rate. A 10% yield is the reciprocal of a 10-times multiple; a 4% yield is the reciprocal of 25 times. It also makes comparisons across different measures easier to state. But the resemblance to a bond yield ends at the arithmetic. A bond's contractual coupon and principal claim aren't the same thing as a business's future earnings or cash flow. A stock yield records a ratio observed today. It promises no payment.
The inverse form also exposes an important limitation of multiples. A low multiple and a high yield can arise because the market expects the business to shrink, needs to refinance, faces a weak industry, or has reported an unusually strong period that will not repeat. The calculation is a description of the current relationship between a numerator and a price. The explanation for that relationship still has to be researched.
Match the numerator to the claim
Market capitalization is the market value of common equity: share price multiplied by shares outstanding. It is the price of the residual claim after debt holders and other senior claimants have been paid. A cash-flow measure that already reflects interest and tax belongs at this level.
Enterprise value is a practical estimate of the price of the operating business regardless of whether it was financed with debt or equity. A simple version is:
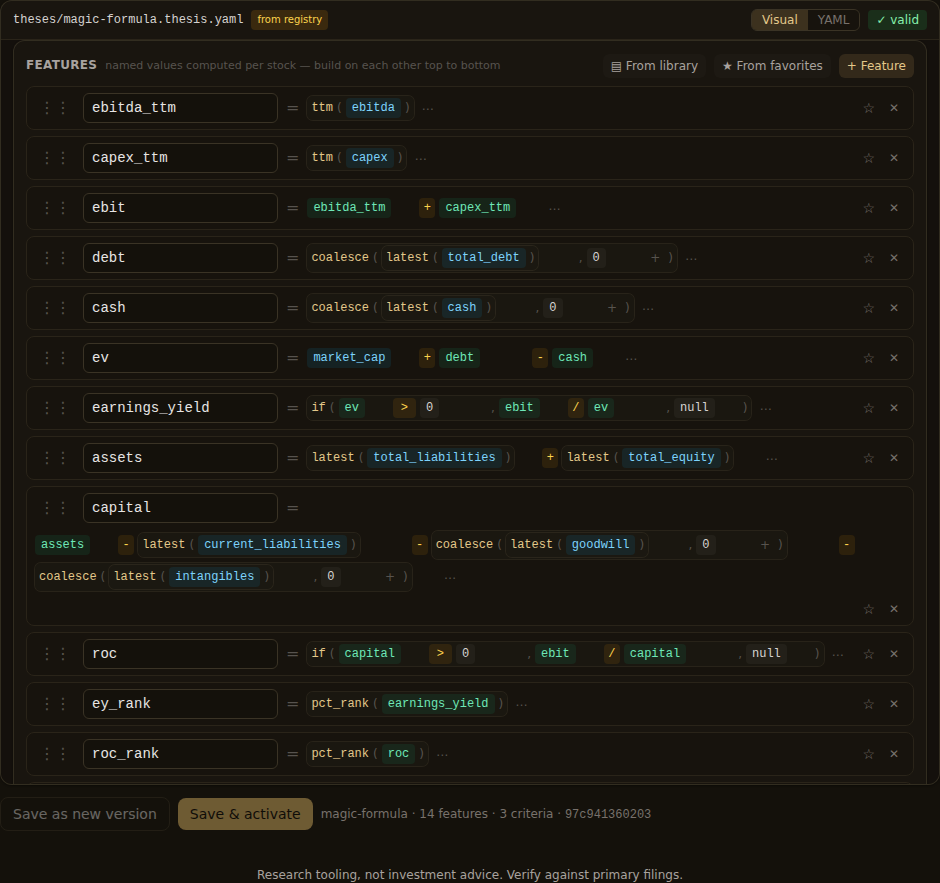
enterprise value = market capitalization + total debt - cashIt's deliberately a simplification. Depending on the company and the question, leases, preferred stock, minority interests, pensions, or restricted cash can matter. Still, the simple calculation establishes the key matching principle. EBIT and EBITDA are operating measures before interest expense, so they don't assign the business's output between lenders and shareholders. They belong over enterprise value. That is why EBITDA needs a capital-charge companion, and why its valuation counterpart is EBITDA/EV instead of EBITDA divided by market cap.
Free cash flow needs its definition stated before it enters the ratio. In the cash-statement version used by many basic screens, it is operating cash flow minus capital expenditures. Operating cash flow has already incorporated cash interest and taxes, so this is commonly used as an equity-level cash measure over market capitalization:
free-cash-flow yield = free cash flow / market capitalization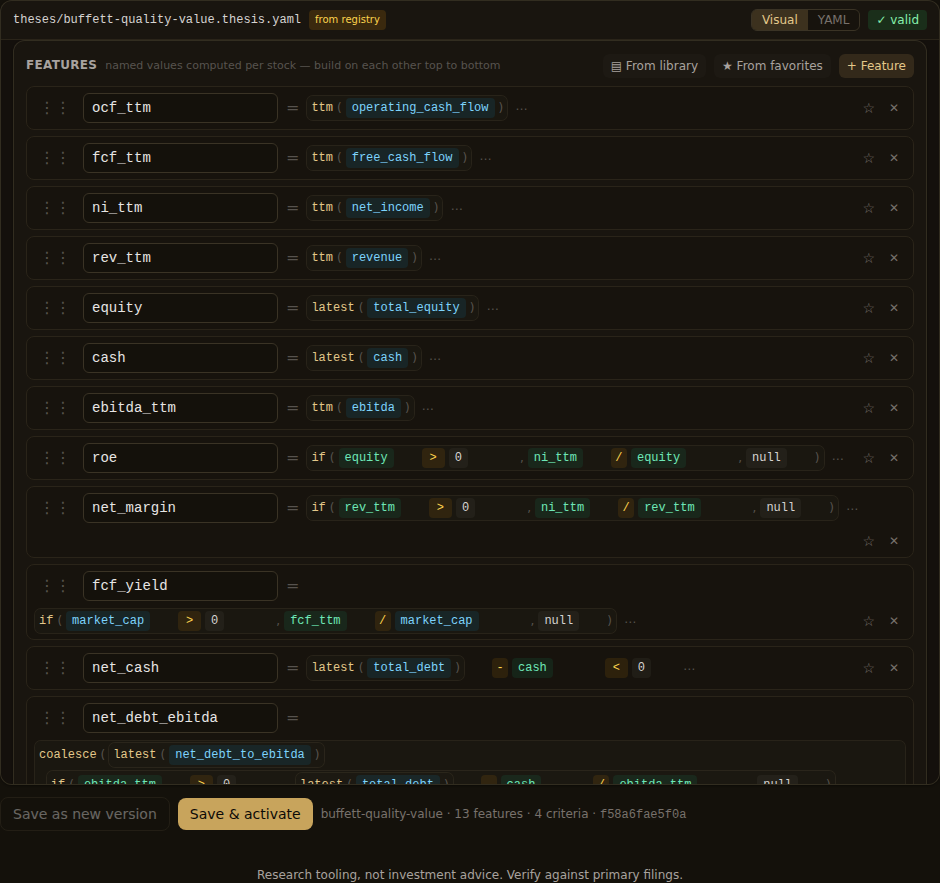
An unlevered free-cash-flow definition is a different numerator. If interest is added back to create cash flow before debt service, it is a firm-level measure and should be paired with enterprise value instead. The label alone cannot settle this. Read the construction of the numerator, then choose the denominator that prices the same set of claimholders.
Two tempting mismatches show why this matters. EBITDA divided by market cap ignores the debt claim while using earnings before debt service, which can make a heavily indebted company look unusually cheap. Cash flow after interest divided by EV does the reverse: it puts an equity-level numerator over a denominator that includes debt. Neither mistake is repaired by adding more decimal places.
A public-record example separates price from capital
Berkshire Hathaway's 2007 shareholder letter recounts its 1972 purchase of See's Candies for $25 million. The letter says See's then earned pre-tax profits of just under $5 million and that the capital required to run the business was $8 million, which the letter describes as a 60% pre-tax return on invested capital. Those figures create two very different ratios from the same business: a pre-tax earnings-on-price yield just under 20% (a little under $5 million divided by $25 million) and the 60% pre-tax return on operating capital (the same earnings divided by $8 million). Berkshire's letter supplies the underlying figures.
Don't treat an acquisition made decades ago as a comparable scan result. Keep the questions separate. The first ratio relates output to the purchase price. The second relates output to the capital employed in the business. A company can earn a high return on its operating capital and still be expensive at a particular market price. It can also trade at a high earnings yield while its underlying capital economics are deteriorating. Yield measures price against output; return on capital measures output against capital. Put them beside each other in the thesis and keep them out of the same fraction.
A high yield starts a question
A high yield can be the opening line of a useful hypothesis: perhaps the market price is lower than the business's durable cash generation would justify. It can just as easily be the market's judgment that the numerator is temporarily high or about to fall. The ratio itself does not choose between those stories.
Start by reading the numerator through the filings. For an EBITDA/EV screen, compare the EBITDA add-back with depreciation and the cash spent on assets. A capital-heavy company can look inexpensive on EBITDA precisely because the ratio excludes a recurring capital requirement. For an FCF yield, check the working-capital movements, asset spending, and whether a one-off release of cash inflated the trailing period. Free cash flow is not an earnings-quality shortcut; its construction still needs to be inspected.
Then read the denominator. Debt can change the apparent cheapness of the equity without making the whole business cheaper. Cash can be needed for operations, pledged, or offset by obligations not captured in a simple formula. A screen cannot resolve every capital-structure detail, but it can prevent a basic mismatch from becoming the basis of the research.
Finally, make the claim narrow enough to test. "Companies with a positive, matched yield and durable cash conversion have a pattern worth investigating" is a testable proposition. "A high yield means the market is wrong" is not. The second sentence smuggles a forecast into a calculation.
Turn the matching rule into a test
Quantery's bundled Magic Formula template uses the name earnings_yield for an EBIT-over-EV feature. The Earnings Yield + Quality template calls its EBITDA-over-EV feature ebitda_ev_yield, and other bundled templates use fcf_yield for free cash flow over market capitalization. Those names keep the level of each ratio in view instead of leaving it implicit.
The shape below is illustrative. The bundled templates and the DSL reference are the reference for exact fields and supported expressions. It keeps firm-level and equity-level yields separate on purpose.
# Matched valuation yields, illustrative only
features:
  ebit_ttm: ttm(operating_income)
  ebitda_ttm: ttm(ebitda)
  fcf_ttm: ttm(free_cash_flow)
  cash: latest(cash)
  debt: coalesce(latest(total_debt), 0)
  ev: market_cap + debt - cash

  earnings_yield: if(ev > 0, ebit_ttm / ev, null)
  ebitda_ev_yield: if(ev > 0, ebitda_ttm / ev, null)
  fcf_yield: if(market_cap > 0, fcf_ttm / market_cap, null)

criteria:
  usable_inputs:
    rules:
      - { when: "ev > 0 and fcf_ttm > 0", score: 1 }
      - { else: 0 }

gate:
  mode: strict
The guards matter. A nonpositive enterprise value or market capitalization won't produce an extreme bargain score; it produces a missing ratio. Requiring positive trailing free cash flow is one possible research choice. It isn't a universal quality stamp. A different study might retain negative-cash-flow businesses and test them separately, so their economics aren't hidden behind a null.
Once the formula says exactly what it means, test the premise across time instead of treating a current ranking as an answer. Use point-in-time filing data, retain the conditions that would've been knowable on each date, and examine whether a parameter change overturns the result. What a backtest can establish is narrower than a forecast: a hypothetical record of stated rules, with costs excluded. That's still enough to reject a fragile ratio or earn a more careful look at a surviving one.
A valuation yield does not tell you what a stock will do. It gives you a disciplined way to ask what price is being paid for a defined claim. Match that claim to its denominator, inspect why the number is high or low, and keep the rule visible enough to test.
Research tooling, not investment advice. Nothing here is a recommendation to buy, sell, or hold any security. Screens, scores, and backtests are informational only; backtested results are hypothetical, exclude costs such as commissions and slippage, and do not guarantee future results. Verify against primary filings and make your own decisions.
Want to try this on your own rules? Quantery is free for 14 days: the full app, no card required.
← All articles