Enterprise value: what the whole business costs
Enterprise value is the market value of a company's equity, plus its debt, minus its cash. It answers a different question from market capitalization. Market cap tells you what the listed shares cost. Enterprise value estimates what the operating business costs once you account for the lenders and the cash already inside the company.
That's the direct answer. The useful part is the bridge between those two figures, because it stops you comparing the earnings of an entire firm with the price of only its common stock. Enterprise value, usually shortened to EV, is how firm-level earnings and firm-level price get onto the same footing.
The bridge builds on gross debt versus net debt, where the same debt-minus-cash adjustment first appeared, and on how to read a balance sheet, where those two inputs live.
How do market cap and enterprise value differ?
Market capitalization is simple:
market cap = share price × shares outstandingIt is the quoted value of the common equity. If you acquired every common share, that is the piece you would pay to the shareholders. You wouldn't thereby make the company's other claims disappear. Its lenders would still expect repayment, and any cash on its balance sheet would now belong to you through the company.
The basic enterprise-value bridge writes those adjustments down:
enterprise value = market cap + total debt - cashAdd debt because it is a senior claim on the same operating assets that produce the earnings. Subtract cash because cash isn't one of those operating assets, and an acquirer receives it with the company. Another way to read the formula is market cap + net debt.
Picture two companies with equal market caps and identical factories. One has no borrowings. The other borrowed heavily and distributed the proceeds to its shareholders. Their equity prices can match while the total market value attached to their operations doesn't. EV exposes the second company's extra claim.
Now reverse it. Give the first company a cash pile larger than its debt. Its enterprise value falls below its market cap. The shares include ownership of that cash, but the operating business is being valued at the equity price less the net cash that comes with it.
That is why EV can be negative. It happens when cash exceeds market cap plus debt under the simple formula. The arithmetic isn't claiming that the business has negative worth. It says the market is valuing all the equity below the net cash on the balance sheet. Before getting excited, find out whether the cash is usable and whether the business is consuming it.
What does an acquisition reveal about EV?
An acquisition makes the bridge concrete because the equity owners and lenders show up in the same announcement.
On May 26, 2022, Broadcom announced its agreement to acquire VMware in a company release hosted by the SEC. The release said the cash-and-stock transaction valued VMware at approximately $61 billion, then separately said Broadcom would assume $8 billion of VMware net debt. Adding those disclosed pieces produces an approximate $69 billion whole-business bridge.
That final sum is derived arithmetic. The release does not use it as a transaction label, and it does not call its first figure equity value. The separate net-debt term still makes the lesson visible: the amount quoted for a transaction can sit beside another claim that follows the acquired operations.
Real transactions involve more detail than the classroom formula. Merger consideration can use diluted shares and stock awards. Debt may be repaid, refinanced, or assumed. The acquirer may keep only part of the cash. The simple bridge is a starting reconciliation, not a substitute for reading the terms.
Where do EV's inputs come from?
The price and share count give you market cap. Debt and cash come from the balance sheet, which is a snapshot on one date.
Total debt means interest-bearing borrowings: short-term debt, the current portion of long-term debt, and the long-term portion. It does not mean total liabilities. Accounts payable and deferred revenue are real obligations, but adding every liability to EV would count ordinary operating finance without making the corresponding operating-asset adjustments.
Cash usually means cash and cash equivalents. A richer version may also subtract short-term investments. The simple Quantery templates use the cash field, so the rule stays reproducible across companies. This is a definition choice, and it belongs in view.
Use balance-sheet inputs from one filing. newest(total_debt) beside newest(cash) gives you a coherent snapshot. A permissive lookup that reaches back for a missing debt figure but takes this quarter's cash can manufacture a capital structure the company never had.
Market cap creates a separate timing issue. Today's price paired with the latest filed debt and cash is a present-day approximation using a lagged balance sheet. That is unavoidable between filings. In a point-in-time backtest, every term must instead be the term available on the simulated date. Letting today's share count or a later balance sheet leak backward spoils the result even if the formula is right.
Why do EV multiples match operating earnings?
A valuation ratio needs a numerator and denominator that belong to the same group of capital providers.
Net income is what remains for common shareholders after interest expense. It is an equity-level earnings figure, so price-to-earnings compares net income with equity value. Free cash flow is commonly treated the same way in a simple screen, which is why an FCF yield uses market cap.
EBIT and EBITDA sit before interest. EBIT is earnings before interest and taxes. EBITDA adds depreciation and amortization back to EBIT. Both describe operating earnings before the split between lenders and shareholders, so compare them with enterprise value:
EBIT / enterprise value
EBITDA / enterprise value
Those are earnings yields. Their inverted forms are the familiar EV/EBIT and EV/EBITDA multiples. You can choose either direction, but don't mix levels. EBIT over market cap makes an indebted company look cheaper because the numerator includes earnings available to service debt while the denominator pretends the debt claim isn't there.
EV doesn't make EBITDA better. As the EBITDA article explains, adding back depreciation can flatter a business that must spend heavily on physical assets. The matching is correct, and the earnings measure may still be poor. Those are separate questions.
How does a Quantery thesis calculate EV?
The Greenblatt Magic Formula and Earnings Yield + Quality templates both build the bridge in their features. The first uses it to calculate EBIT over EV, then ranks that yield against the rest of the selected universe. The second uses EBITDA over EV and tests absolute yield bands.
In the Greenblatt template, the core reads:
features:
  debt: coalesce(latest(total_debt), 0)
  cash: coalesce(latest(cash), 0)
  ev: market_cap + debt - cash
  earnings_yield: if(ev > 0, ebit / ev, null)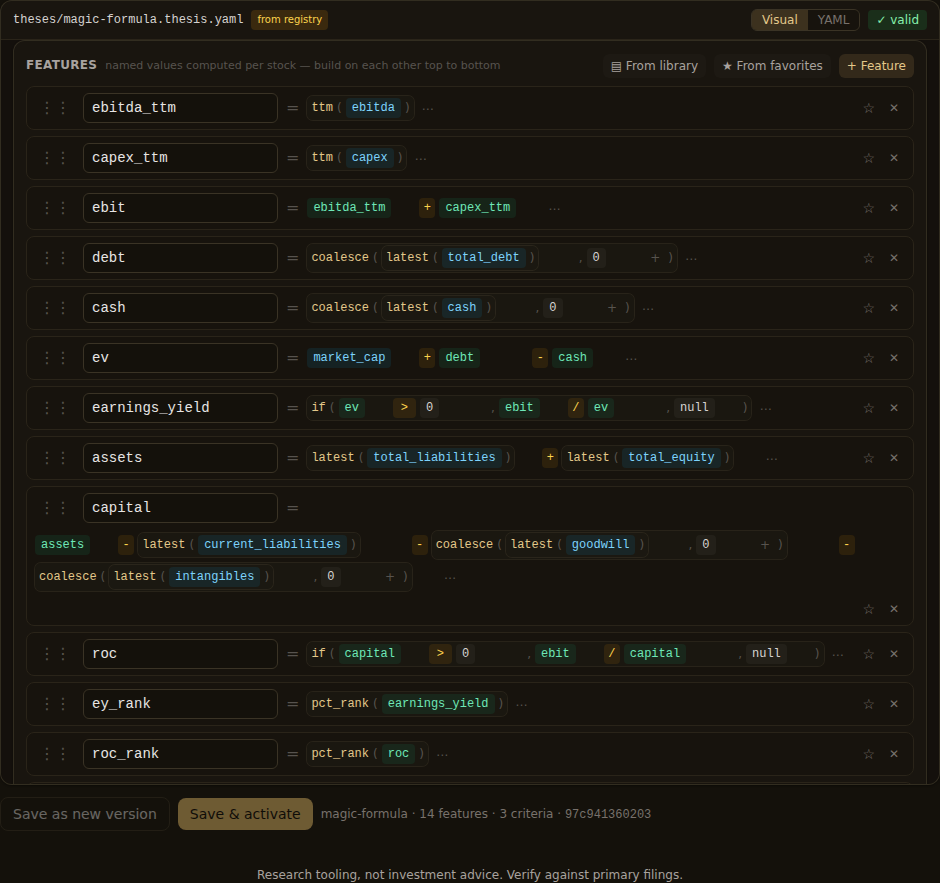
The ev > 0 guard deserves its line. A zero or negative denominator doesn't produce a magical bargain yield. It produces a ratio that has stopped carrying its intended meaning, so the template returns null. Missing values deserve the same attention. The template treats absent debt or cash as zero, a practical convention for line items that often disappear when there is none. If a source failed to collect a real balance, that convention is wrong. Open the survivor detail and inspect the filing before leaning on an extreme result.
Here is a fuller illustrative shape. The bundled in-app templates remain the reference for exact fields and options, while the public documentation explains the shape of a Quantery thesis.
# "Operating earnings at a sensible firm value" - illustrative
params:
  yield_strong: 0.10
  yield_ok: 0.06

features:
  ebit_ttm: ttm(operating_income)
  debt:     newest(total_debt)
  cash:     newest(cash)
  ev:       market_cap + debt - cash
  ey:       if(ev > 0, ebit_ttm / ev, null)

criteria:
  operating_earnings_yield:
    rules:
      - { when: "is_null(ey) or ebit_ttm <= 0", score: 0, flag: no_valid_yield }
      - { when: "ey >= $yield_strong", score: 2 }
      - { when: "ey >= $yield_ok", score: 1 }
      - { else: 0 }

gate:
  mode: strict
The thresholds are proposed parameters. Keep them round, vary them, and test whether the result survives. Better still, compare a fixed yield rule with a percentile rank. A fixed bar can return no qualifying names when the whole market is expensive. A rank will always identify the cheaper end of its universe, even when that end isn't cheap in absolute terms.
What does simple EV leave out?
The one-line formula is useful because it is inspectable. It is incomplete for the same reason.
Preferred stock and minority interest. Preferred holders have claims ahead of common equity, while minority interest represents outside ownership in subsidiaries whose operating earnings may be fully consolidated. More complete EV definitions add both.
Leases and pensions. A long store lease behaves a lot like debt, and an underfunded pension is another claim on future cash. The simple debt field doesn't capture either in full.
Cash that isn't excess. Payroll cash, restricted cash, regulatory capital, and money committed to an announced deal can't all be swept out on closing day. Subtracting every dollar can make EV look too low. The net-debt article covers this judgment in detail.
Stale capital structure. A company can issue debt, repurchase shares, or close an acquisition after its last balance-sheet date. EV built from the old filing won't see the change yet. Read subsequent-events notes and recent filings when the ratio looks exceptional.
Financial businesses. Debt is raw material for a bank, and cash can be regulatory or customer funding. Pulling both out of the operating business doesn't work cleanly. That is why the bundled EV-based templates exclude Financial Services and Real Estate, with Utilities excluded where their capital structure makes the quality comparison unhelpful.
Enterprise value won't tell you what a business is worth. It won't decide whether reported operating earnings are durable. It does one narrower job: it names the claims attached to those earnings and puts their market value in the denominator. Once the bridge is visible, you can change the cash definition, add the claims you care about, and re-test the yield. The rules are yours, including the parts the simple formula leaves out.
Research tooling, not investment advice. Nothing here is a recommendation to buy, sell, or hold any security. Screens, scores, and backtests are informational only; backtested results are hypothetical, exclude costs such as commissions and slippage, and do not guarantee future results. Verify against primary filings and make your own decisions.
Want to try this on your own rules? Quantery is free for 14 days: the full app, no card required.
← All articles